When it comes to auto insurance in Massachusetts, understanding the intricate details can feel like navigating a labyrinth. But fear not, because knowing the ins and outs of what you’re paying for can save you money and ensure you’re adequately protected.
In this guide, we’ll break down everything from the basic requirements to the cost comparisons and strategies to keep your premiums low, all with a touch of Backlinko’s signature style. Let’s dive in!
Overview of Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the strictest auto insurance requirements in the U.S.? Whether you’re a new driver or just moved to the state, understanding these requirements is crucial.
Massachusetts law mandates that every driver must carry a minimum level of auto insurance. This includes Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property. But here’s the deal: these are just the basics.
Coverage Options Available in Massachusetts
Beyond the mandatory coverage, you have options. Comprehensive and Collision coverage can protect you against theft, vandalism, and accidents. Medical Payments and Underinsured Motorist coverage are also worth considering. Why? Because they can save you from financial fallout in worst-case scenarios.
But, choosing the right policy can be confusing. That’s where the Massachusetts Division of Insurance steps in. They regulate the industry to ensure you’re getting a fair deal.
The Role of the Massachusetts Division of Insurance
The Division of Insurance is your go-to resource for understanding rates, complaints, and company ratings. They keep tabs on insurers to ensure fair practices. And if you’re ever in a bind, they can help resolve disputes.
But, what really impacts your insurance rates? Several factors are at play.
Factors Influencing Insurance Rates in Massachusetts
Age, driving history, and even your credit score can affect your rates. For instance, younger drivers or those with a history of accidents may see higher premiums. Conversely, a clean driving record can be your ticket to discounts.
Pro Tip: Bundle your auto insurance with other policies like home or renters insurance for potential savings.
Location matters too. Urban areas might have higher rates due to increased risk of accidents and theft. So, if you’re thinking about moving, consider how it might impact your insurance costs.
Average Cost of Auto Insurance in Massachusetts
Did you know that Massachusetts is one of the most expensive states for auto insurance in the U.S.? On average, drivers here pay a premium for coverage.
According to recent data, the average cost of auto insurance in Massachusetts is around $1,460 per year. That’s significantly higher than the national average of $1,251. But why is that the case?
Breaking Down the Cost: Coverage and Providers
Not all auto insurance policies cost the same. In Massachusetts, your premium depends on the type of coverage you choose and the provider you go with. Let’s break it down.
| Coverage Level | Average Annual Cost | Major Providers |
|---|---|---|
| Minimum Coverage | $800 | Geico, Progressive |
| Full Coverage | $1,700 | Liberty Mutual, State Farm |
The choice between minimum and full coverage is just one factor. The provider you choose can also make a big difference in what you pay.
Geographical Variations Within Massachusetts
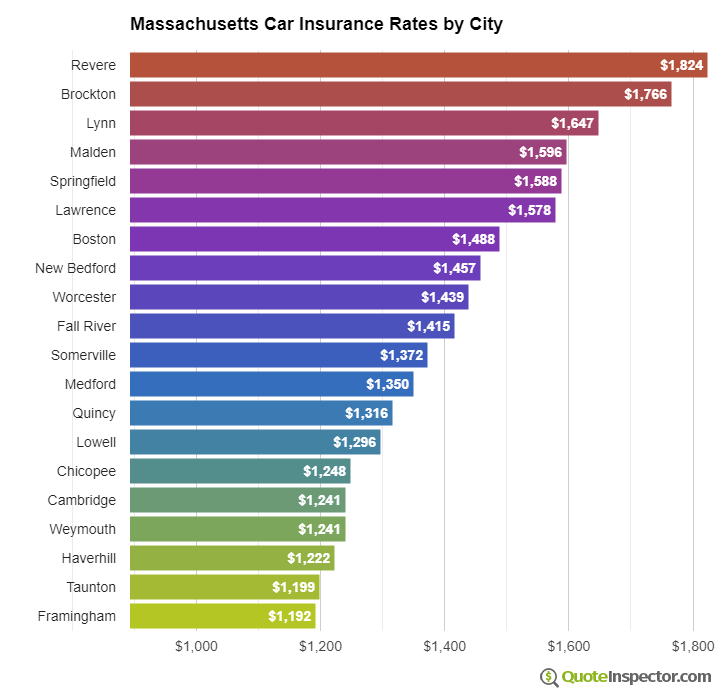
Insurance rates aren’t just a statewide average—they vary widely from city to city. For instance, drivers in Boston pay more than those in Springfield.
What’s driving these differences? It’s a mix of factors like population density, crime rates, and even weather patterns. Urban areas tend to have higher accident rates, pushing premiums up.
Pro Tip: If you live in an expensive area, consider bundling your auto insurance with other policies to save.
Factors Influencing Auto Insurance Rates
Ever wondered why your auto insurance rates are through the roof while your friend’s are a steal? It boils down to several key factors that insurers love to analyze.
From your driving history to the type of car you drive, and even your zip code, each plays a pivotal role in determining your insurance premium in Massachusetts.
Impact of Driving History on Insurance Premiums
Your driving history is more than just a record; it’s your insurance report card. If you have a clean slate, expect lower rates. BUT speed tickets or accidents? Brace for a hike.
Insurance companies in Massachusetts consider how many incidents you’ve had in the last few years. The more claims or infractions, the higher the risk they associate with you, which translates to higher premiums.
Influence of Vehicle Type on Insurance Costs
Not all cars are created equal, especially in the eyes of insurers. Your beloved sports car might be a thrill to drive, but it’s also a magnet for higher insurance costs.
Insurers look at the make and model of your vehicle. Fancy, high-performance cars or those with a higher theft rate typically cost more to insure. Meanwhile, safe and reliable cars often get you better deals.
Effect of Location on Insurance Rates
Where you park your car overnight can significantly affect your insurance premium. Yes, your zip code matters!
Urban areas in Massachusetts with higher traffic and crime rates tend to have steeper insurance costs. Let’s compare:
| Region | Average Annual Premium |
|---|---|
| Boston | $1,900 |
| Springfield | $1,700 |
| Worcester | $1,500 |
Pro Tip: Pay attention to your driving habits and consider where you live, as both can dramatically reduce your insurance costs.
How to Reduce Auto Insurance Costs
Paying too much for auto insurance? You’re not alone. Many drivers overpay just because they don’t know how to cut down on costs.
Let’s dive into some actionable strategies. You’ll be amazed at how much you can save with a few simple tweaks!
Methods for Lowering Auto Insurance Premiums
The first step to reducing your insurance bill is comparing quotes from different providers. Don’t settle for the first offer you get. Remember, insurers compete for your business, and you should take advantage of that!
Pro Tip: Bundle your auto insurance with other policies, like homeowner’s insurance, to snag extra discounts.
Available Discounts for Safe Drivers and Students
Safe driving pays off. If you’ve got a clean driving record, you’re in luck. Insurers often offer substantial discounts to those who prove they’re low-risk.
Students, listen up! If you maintain good grades, you might qualify for an educational discount. Now, who said studying doesn’t pay?
Strategies for Improving Credit Scores to Reduce Costs
Did you know your credit score can impact your insurance rates? A higher score typically means lower premiums. Here’s the deal: work on paying down debt and making payments on time.
Boosting your credit score not only saves you money on loans but also shaves dollars off your insurance bill.
Tips for Maintaining a Low-Risk Profile
Keeping a low-risk profile is key to long-term savings. Here are some tips to help you maintain it:
- Avoid speeding and traffic violations.
- Install anti-theft devices in your vehicle.
- Take a defensive driving course.
- Limit your annual mileage.
- Park in a secure location overnight.
Comparing Auto Insurance Providers in Massachusetts
Ever wondered how auto insurance providers in Massachusetts stack up against each other? You’re in the right place. Let’s dive into the nitty-gritty of comparing the top players in the Bay State.
Choosing an auto insurance provider isn’t just about the price. It’s also about the benefits, drawbacks, and customer satisfaction each one offers. Here’s the deal: a better understanding of these aspects can save you a ton of money and headaches down the road.
Comparison of Popular Providers
Here’s a quick look at how some of the most popular insurance providers in Massachusetts compare:
| Provider | Average Annual Premium | Unique Benefits | Drawbacks |
|---|---|---|---|
| Geico | $1,200 | Low rates, easy online access | Limited local agents |
| Liberty Mutual | $1,450 | Extensive coverage options | Higher rates for some drivers |
| Progressive | $1,350 | Snapshot program for discounts | Mixed customer service reviews |
| State Farm | $1,500 | Strong agent network | Fewer discounts compared to others |
Customer Satisfaction and Service Quality
Your experience with an insurance company can be as important as the price you pay. In Massachusetts, customer satisfaction varies widely among providers.
Pro Tip: Don’t just consider the premium—look at the service quality too.
Geico and Progressive often score high with tech-savvy consumers, while State Farm shines with personalized agent support.
Additional Services Offered
Beyond basic policies, additional services can significantly enhance your insurance experience. Liberty Mutual, for instance, offers a unique accident forgiveness program, while Geico provides emergency roadside assistance. But here’s the kicker: these extras can sometimes tip the scales when deciding between two providers.
Legal and Financial Implications of Auto Insurance
What happens if you don’t have auto insurance in Massachusetts? It’s not just risky; it’s illegal. Understanding the legal and financial implications can save you from hefty fines and financial ruin.
Auto insurance isn’t just a good idea; it’s a legal requirement in Massachusetts. Without it, you could face significant penalties and financial liabilities. Let’s break it down.
Legal Requirements for Auto Insurance in Massachusetts
In Massachusetts, carrying auto insurance is non-negotiable. At a minimum, you must have liability coverage to cover bodily injury and property damage. This means if you cause an accident, your insurance helps pay for the other party’s expenses. However, just meeting the basic requirement might not be enough to protect your assets.
Penalties for Non-Compliance
Think you can skip out on insurance? Think again. Driving without auto insurance in Massachusetts can result in fines up to $5,000, a suspended license, and even jail time. It’s not worth the risk. Plus, you could end up paying out of pocket for damages or injuries resulting from an accident you cause.
Financial Responsibility and Liability Coverage
Auto insurance isn’t just about following the law; it’s about financial responsibility. If you’re at fault in an accident, liability coverage helps protect your wallet from potentially bankrupting expenses like medical bills and legal fees. It’s essential to consider coverage limits that reflect the value of your assets. The more you have, the more you stand to lose.
Handling Claims and Disputes
Accidents happen, and when they do, filing a claim can seem daunting. Here is the deal: it’s crucial to report the incident to your insurance provider as soon as possible. Provide accurate information, and be ready to negotiate with the insurer if needed. If you face a dispute, Massachusetts offers mediation services to help resolve issues without heading to court.
Pro Tip: Always keep detailed records of any communication with your insurer. It can be your best ally in a dispute.
Conclusion
Wrapping up, navigating the auto insurance landscape in Massachusetts doesn’t have to be overwhelming. With the right knowledge and strategies, you can find an insurance policy that not only meets legal requirements but also fits your budget. Remember, being informed is your best tool in securing the best coverage at the best price.
Q&A
What are the minimum auto insurance requirements in Massachusetts?
Massachusetts requires drivers to have a minimum level of coverage, including bodily injury liability, personal injury protection, and property damage liability.
How does Massachusetts auto insurance compare to the national average?
Auto insurance in Massachusetts is generally above the national average due to factors such as population density and the number of drivers.
What factors affect auto insurance rates in Massachusetts?
Rates are influenced by factors such as the driver’s age, driving history, type of vehicle, and location within the state.
Can I reduce my auto insurance costs in Massachusetts?
Yes, you can reduce costs by taking advantage of discounts for safe driving, bundling policies, and improving your credit score.
Are there penalties for not having auto insurance in Massachusetts?
Yes, driving without insurance can result in fines, license suspension, and increased premiums once coverage is obtained.
